Garment processing for foreign enterprises is a business sector that has been developing vigorously in the Vietnamese market in recent years. Through the following article, NPLaw would like to provide our readers with useful legal insights related to garment processing activities for foreign enterprises.
Garment processing for foreign enterprises is a business sector that has been developing vigorously in the Vietnamese market in recent years. Through the following article, NPLaw would like to provide our readers with useful legal insights related to garment processing activities for foreign enterprises.
I. Demand for garment processing for foreign enterprises
Vietnam is one of the world’s major and most preferred processing markets, particularly in the garment sector, due to its relatively low labor costs compared to many developed countries, enabling enterprises to significantly reduce production costs. With the recovery of the economy following the COVID-19 pandemic, demand for garment products has been increasing again, creating favorable opportunities for garment processing enterprises in Vietnam.
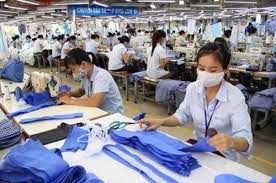
At present, the demand for garment processing for foreign enterprises in Vietnam remains very high. According to data from the General Statistics Office of Vietnam, the textile and garment industry is among the sectors with the highest export turnover, reaching approximately 39 billion USD in 2023.
It is anticipated that garment processing activities will continue to account for a substantial proportion of Vietnam’s total export turnover, further demonstrating the strong and growing demand for garment processing services for foreign enterprises in Vietnam in the future.
II. Regulations related to garment processing for foreign enterprises
1. What is garment processing for foreign enterprises?
Garment processing for foreign enterprises is a business arrangement whereby a Vietnamese enterprise receives raw materials and accessories from a foreign enterprise and conducts processing and manufacturing to produce finished products in accordance with the foreign partner’s requirements. The finished products are subsequently exported back to the foreign country or to other markets as agreed upon in the processing contract.
2. Main issues to note when processing garments for foreign enterprises
When engaging in garment processing for foreign enterprises, the following issues should be carefully considered:
- Processing objects and scope: All types of goods, except those subject to prohibitions on business, export, or import, are permitted for processing. However, with permission from competent state authorities, goods that are otherwise prohibited from business, export, or import may still be processed for foreign traders (Article 180, Law on Commerce 2005).
- Processing remuneration: Remuneration may be paid in cash or in kind, including processed products, machinery, or equipment used for processing.
- Export and import procedures: Export and import activities must comply with regulations on export and import management, including the temporary import and re-export of machinery, equipment, raw materials, accessories, and supplies, or transshipment of such items from a third country to the processing recipient or processing party for the execution of the processing contract.
- Taxes and fees: Taxes and fees applicable to the import of raw materials, export of finished products, as well as quality management and customs inspection, must comply with relevant legal regulations.
3. Essential contents of the garment processing contract for foreign enterprises
When drafting the garment processing contract for foreign enterprises, the following essential contents should be included:
- Subject matter of the contract;
- Information of the contracting parties;
- Specific tasks and obligations to be executed by each party;
- Timeframe for performance of the work;
- Time of delivery of finished products;
- Rights and obligations of the parties:
- Payment method;
- Liability and sanctions for breach of contract;
- Force majeure;
- Unilateral termination of the contract;
- Processing remuneration in accordance with Article 184 of the Law on Commerce 2005.
III. Questions regarding garment processing for foreign enterprises
1. What taxes must the garment processing company for foreign enterprises pay?
Pursuant to Clause 1 Article 10 of Decree No. 134/2016/NĐ-CP, goods imported for processing and processed products exported under a processing contract are exempt from export and import duties.
Pursuant to Clause 1 Article 9 of Circular No. 219/2013/TT-BTC guiding the Law on Value-Added Tax and Decree No. 209/2013/NĐ-CP, imported and exported processed goods that are not consumed domestically are subject to a value-added tax (VAT) rate of 0%.
As the garment processing enterprise generates profits from its business activities, it is subject to corporate income tax in accordance with the current Law on Corporate Income Tax 2008.
Accordingly, garment processing companies for foreign enterprises are subject to corporate income tax and 0% VAT.
2. Which business lines must the garment processing company for foreign enterprises register?
Garment processing for foreign enterprises requires the processing contractor to import raw materials from the foreign requesting party and subsequently export the processed products back to the requesting party.
Accordingly, garment processing companies for foreign enterprises should register the following business lines:
- Goods processing services;
- Import and export trading activities.
3. If garment processing products for foreign enterprises are delivered late, is compensation required?
Pursuant to Article 303 of the Law on Commerce 2005, the basis for liability for damages includes the occurrence of a contractual breach, actual damage suffered, and a direct causal relationship between the breach and the damage.
Late delivery of products compared to the schedule agreed upon in the contract constitutes a breach of contract and may cause damage to the requesting party.
Accordingly, if garment processing products for foreign enterprises are delivered late, the processing contractor may be required to compensate for damages.
4. If the garment processing shipment is affected by natural disasters and cannot be delivered, what should be done? Is compensation required if the requesting party does not accept the agreement?
Pursuant to Clause 1 Article 156 of the Civil Code 2015, natural disasters may be considered force majeure, as they are objective events that are unforeseeable and cannot be remedied despite all necessary and permissible measures having been taken.
However, in order to limit potential disputes where the non-breaching party does not agree to recognize a natural disaster as force majeure, when natural disasters prevent the delivery of processed garment products, the breaching party (the processing contractor) should consider undertaking the following actions:
- Promptly sending written notice to the requesting party, describing the impact of the natural disaster and the inability to remedy the consequences;
- Negotiating with the requesting party (the non-breaching party) to agree on recognizing the natural disaster as force majeure;
If the requesting party does not accept such an agreement, the processing contractor may not be subject to sanctions for breach, because:
- Pursuant to Point b Clause 1 Article 294 of the Law on Commerce 2005, where force majeure event, the breaching party is exempt from liability.
- Pursuant to Article 303 of the Law on Commerce 2005, cases of exemption from liability are not subject to compensation for damages under commercial law.
Accordingly, where delivery cannot be made due to natural disasters, the processing contractor may negotiate relevant matters with the requesting party, and if no agreement is reached, the processing contractor may not be required to compensate for damages.
5. Is a contract mandatory when Vietnamese enterprises process garments for foreign enterprises?
Pursuant to Clause 1 Article 45 of Decree No. 98/2020/NĐ-CP, placing or receiving goods for processing with foreign traders without a contract in accordance with regulations constitutes a violation related to processing activities involving foreign elements.
Accordingly, Vietnamese enterprises that undertake garment processing for foreign enterprises are required to enter into a processing contract.
IV. Legal consulting services related to garment processing for foreign enterprises
Understanding the needs of our clients in learning about regulations on garment processing for foreign enterprises, Ngoc Phu Law Company Limited provides professional legal consulting and support services in this field. Our readers are welcome to contact NPLaw to receive prompt and dedicated advice from our experienced lawyers specializing in legal consultancy and procedural matters, using the contact information below: